TV & Video
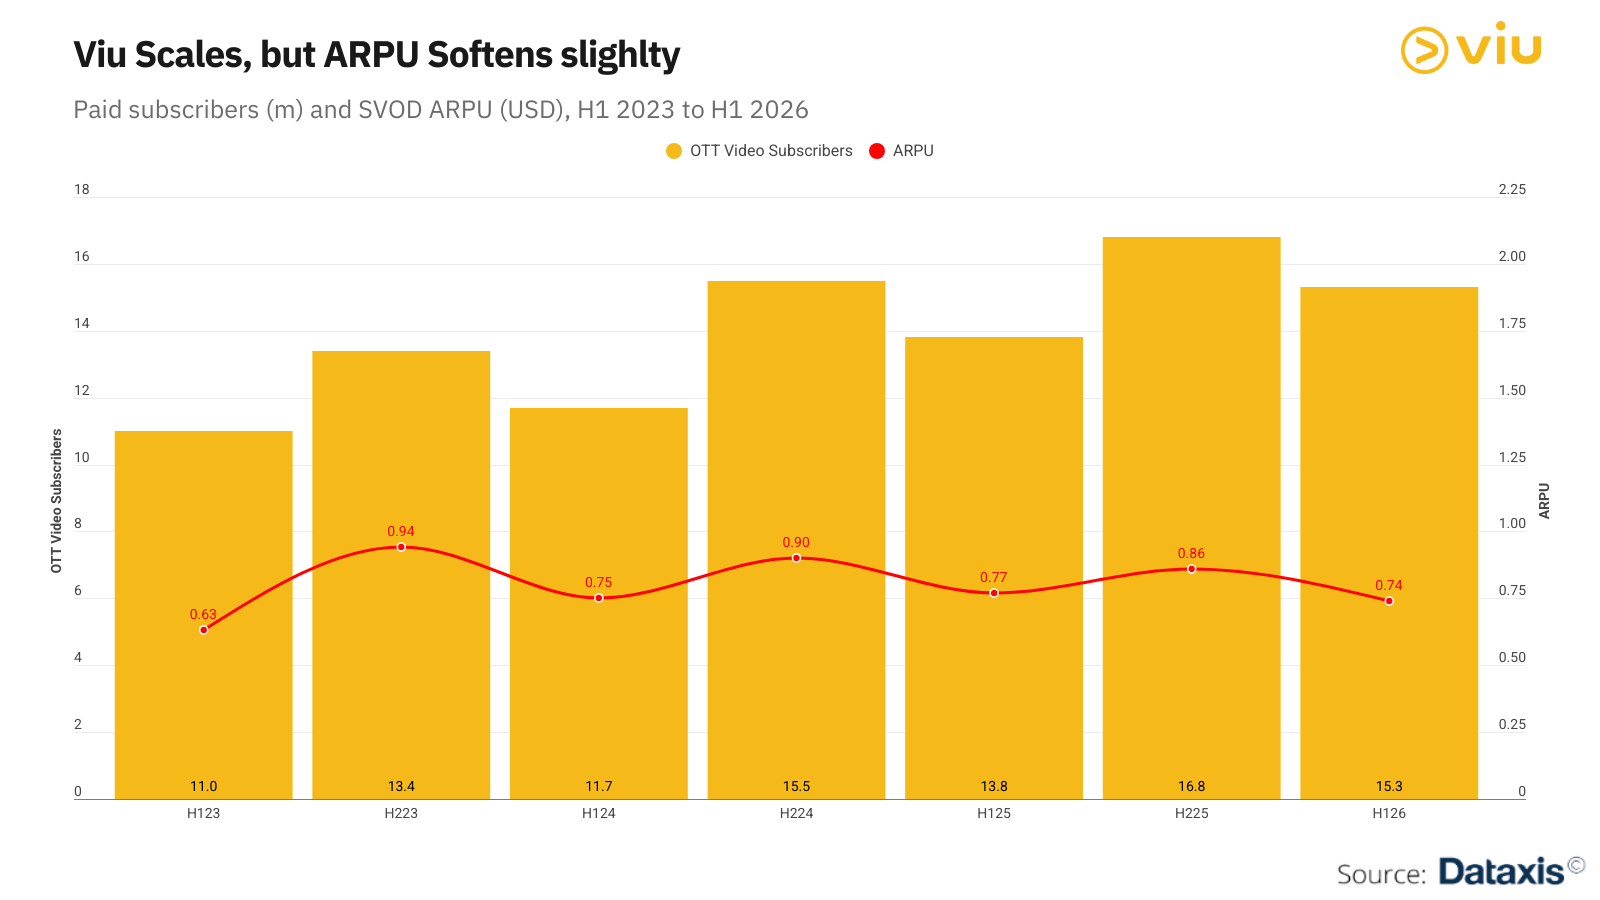
H1 2026 was a mixed period for Viu. Paid subscribers rose a strong 11% year on year, reaching 15.3 million, up from 13.8 million. Yet PCCW’s total OTT revenue fell from USD 153 million to USD 142 million. The EBITDA margin held at 29%, showing that further margin expansion has stalled, although it remains well above 21% in H1 2024 and 17% in H1 2023. With revenue falling, maintaining the same margin shows that cost discipline is protecting profitability rather than driving further profit growth.
SVOD is healthier. Dataxis estimates H1 2026 revenue at USD 71 million, up about 5% from USD 68 million, but well below the 13% growth recorded in FY2025.
Despite wider distribution, ARPU has held up relatively well. Dataxis estimates H1 2026 SVOD ARPU at USD 0.74, down just 3.9% from USD 0.77 a year earlier. That remains below global Hollywood-led platforms, but it is closer to regional services: Vidio generates roughly USD 1.28 ARPU in Indonesia, while Viu sits just slightly above MonoMax in Thailand. The comparison is imperfect across markets, but Viu’s monetisation model is more in line with local platforms than with global premium streamers.
Read the full analysis
Create a free Dataxis account, or sign in, to read this highlight in full.
Create a free account